
DLF Camellias Tax Relief Case: ITAT Rules Discounts Not Taxable
Tribunal Deletes ₹9.81 Crore Addition by Tax Department
Capital Gains Exemption of ₹9.65 Crore Restored
By Legal Reporter
New Delhi: March 21, 2026
In a landmark judgment, the Delhi ITAT has clarified that builder discounts on property purchases cannot be treated as “income from other sources.” The case involved a Gurugram resident who purchased a luxury flat in DLF Camellias for ₹23.13 crore after receiving a discount of ₹9.82 crore on the listed price of ₹32.95 crore. The Income Tax Department had issued a notice, treating the discount as taxable income, but the tribunal struck down the addition.
To understand broader legal principles, refer to this authoritative list of will execution and attestation cases.
Case Background
- Flat Price (Listed): ₹32.95 crore
- Discount Received: ₹9.82 crore
- Final Purchase Price: ₹23.13 crore
- Capital Gains Claimed: ₹9.65 crore under Section 54F
The Assessing Officer (AO) initially denied the exemption and treated the discount as income under Section 56(1). The Commissioner of Income Tax (Appeals) upheld this view, forcing the buyer to appeal before ITAT.
[Recommended Research Resources]
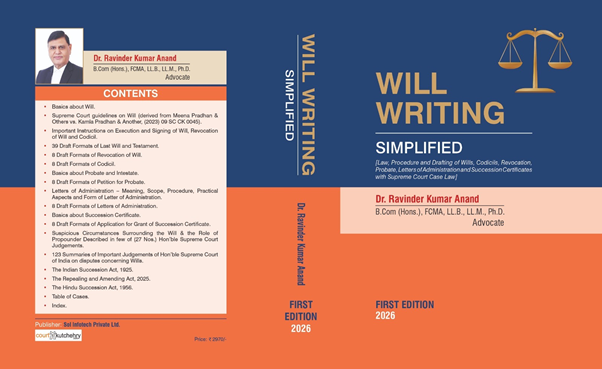
📘 Legal professionals, families and students alike will benefit from Will Writing Simplified, which covers procedure and case law in detail.
🔹 Buy on Amazon
🔹 Buy on Flipkart
Tribunal’s Key Observations
- Discount is contractual, not income: ITAT noted that rebates were linked to timely payments and contractual terms, not independent income.
- Section 56 not applicable: Since the purchase price was higher than the stamp duty value, deemed income provisions did not apply.
- Capital gains exemption valid: ITAT clarified that registration of the property is not mandatory for Section 54F; possession and substantial payment suffice.
- Family arrangement genuine: Transfer of certain properties to the buyer’s wife years earlier was accepted as legitimate, not tax avoidance.
Implications of the Ruling
- Relief for property buyers: Discounts offered by builders in luxury projects will not be taxed as income.
- Clarity on Section 54F: Possession and payment establish ownership for exemption purposes, even without registration.
- Precedent for future cases: The ruling strengthens taxpayers’ position in disputes over rebates and exemptions.
Expert Views
Chartered Accountant Suresh Surana explained that the tribunal’s decision reinforces the principle that rebates are commercial concessions, not income. He added that this ruling will help buyers in similar disputes where the tax department attempts to treat discounts as taxable gains.
Conclusion
The ITAT’s ruling in the DLF Camellias case is a significant victory for taxpayers, especially in high-value real estate transactions. It establishes that builder discounts cannot be taxed as income and that capital gains exemptions under Section 54F remain valid even without property registration.
Keywords for SEO & Faster Searches
DLF Camellias tax case, ITAT ruling property discount, Section 54F exemption, Income Tax Tribunal Delhi, builder rebate not taxable, capital gains relief India, luxury property tax dispute, Gurugram real estate tax case, ITAT Delhi judgment, property discount taxation India.