
ITAT Pune Rules in Favor of Taxpayer: Rs 91.45 Lakh Capital Gains Deduction Restored
Tribunal clarifies Section 54F exemption rules on property investment
Case highlights importance of proper documentation in capital gains claims
By Legal Reporter
New Delhi: February 26, 2026:
In a significant ruling that will impact thousands of taxpayers across India, the Income Tax Appellate Tribunal (ITAT) Pune has overturned an order of the Income Tax Department and allowed a taxpayer to claim a capital gains deduction of Rs 91.45 lakh. The case revolved around the interpretation of Section 54F of the Income Tax Act, which provides tax relief when capital gains are reinvested in residential property.
Also Read: Anthropic Accuses Chinese AI Labs of Distillation Attacks on Claude Models
The tribunal’s decision is being seen as a landmark clarification on how exemptions under Section 54F should be applied, especially in cases where taxpayers invest the entire capital gains into a new property but fail to deposit the sale proceeds into the Capital Gains Account Scheme (CGAS) before filing their income tax return.
[Additional Resource]
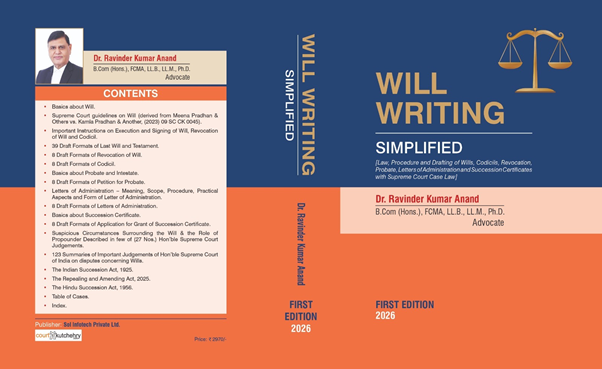
If you want practical guidance on drafting wills, codicils, and probate procedures, Will Writing Simplified is an invaluable resource. BUY TODAY: Amazon 🔹 Flipkart
Background of the Case
Also Read: Visa-Free Travel Explained: Why It Doesn’t Always Guarantee Entry
- The taxpayer, Satishchandra Jagdishchandra Gugale, a resident of Pune, sold a plot of land for Rs 3.21 crore.
- He then purchased a new residential property worth Rs 4 crore.
- While filing his income tax return for Assessment Year 2014–15, he claimed exemption under Section 54F for the capital gains arising from the sale of land.
- The Income Tax Department, however, denied his claim, arguing that he had not deposited the entire sale consideration into the Capital Gains Account Scheme (CGAS) before filing his return.
- As a result, the department disallowed the exemption and raised a tax demand, effectively denying him relief of Rs 91.45 lakh.
Tribunal’s Ruling
The ITAT Pune bench ruled in favour of the taxpayer, stating:
- Full investment matters, not procedural lapses: Since the taxpayer had invested the entire capital gains into the purchase of a new property, he was entitled to exemption under Section 54F.
- CGAS deposit not mandatory if investment is complete: The tribunal clarified that the requirement to deposit unutilized capital gains into the CGAS applies only when the gains are not fully invested before filing the return.
- Substance over form: The tribunal emphasized that tax relief should not be denied merely due to procedural lapses when the intent and action of reinvestment are clear.
This ruling effectively restored the taxpayer’s exemption claim and set aside the Income Tax Department’s order.
Why This Case Matters
- Clarity on Section 54F: The judgment provides much-needed clarity on how Section 54F exemptions should be interpreted.
- Relief for genuine taxpayers: Many taxpayers face similar disputes where procedural errors overshadow genuine reinvestment of capital gains.
- Precedent for future cases: The ruling will serve as a precedent in similar disputes across India, strengthening taxpayers’ position in appeals.
Expert Views
Tax professionals have welcomed the ruling, noting that it reinforces the principle that tax exemptions should be based on actual reinvestment of capital gains rather than strict procedural compliance.
- CA Ajay Kumar Agrawal, writing on TaxGuru, explained that the ITAT’s decision aligns with the spirit of Section 54F, which is to encourage reinvestment in housing rather than penalize taxpayers for technical lapses.
- Experts also believe this ruling will reduce litigation and provide relief to taxpayers who have genuinely reinvested their gains.
Broader Implications
Also Read: Supreme Court Rules Rooh Afza is a Fruit Drink, Attracts Only 4% VAT
- For taxpayers: Those selling land or property and reinvesting in housing can take confidence from this ruling, provided they can prove full reinvestment.
- For the Income Tax Department: The judgment serves as a reminder that tax authorities should focus on substance rather than form when assessing exemptions.
- For legal practitioners: The case highlights the importance of documentation and timely investment to avoid disputes.
Conclusion
The ITAT Pune’s ruling in favour of Satishchandra Gugale is a major victory for taxpayers and a reminder that justice often lies in substance over procedure. By restoring the Rs 91.45 lakh capital gains deduction, the tribunal has reinforced the principle that genuine reinvestment in housing should not be penalized due to technical lapses.
This case will likely influence future disputes and provide clarity for both taxpayers and tax authorities in interpreting Section 54F exemptions.
Keywords for SEO & Faster Searches
Also Read: Kerala High Court: Uploading GST Orders on Portal Constitutes Valid Service
- ITAT Pune capital gains case
- Section 54F exemption India
- Rs 91.45 lakh deduction ITAT ruling
- Capital Gains Account Scheme CGAS
- Satishchandra Gugale vs ITO
- Income Tax Appellate Tribunal property case
- Capital gains reinvestment exemption India
- ITAT ruling on property investment
Also Read: Supreme Court to Examine Condonation of 30-Month ITR Delay