
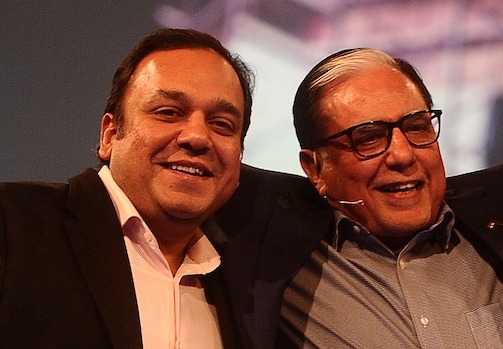
SEBI Cracks Down on Corporate Governance Breaches: Subhash Chandra and Punit Goenka Barred Over Unauthorized ZEEL Asset Pledge
Market Regulator Penalizes Zee Promoters for Mortgaging Hyderabad Land to Cover ₹726 Crore Promoter-Linked Debts Without Board Sanction
Unpacking the Legal Foundations, PFUTP Violations, LODR Mandates, and Governance Imperatives Reshaping Corporate Accountability in India
By Legal Editor
New Delhi: August 01, 2026:
In a watershed ruling for capital market governance in India, the Securities and Exchange Board of India (SEBI) issued a comprehensive 150-page final order barring Zee Entertainment Enterprises Limited () Chairman Emeritus Subhash Chandra and Managing Director & CEO Punit Goenka from accessing the securities market for a period of one year. In addition to the market bans imposed on the controlling promoters, the market regulator restrained itself from accessing the securities market for two months and imposed cumulative monetary penalties totaling ₹1.48 crore—comprising ₹60 lakh on Subhash Chandra, ₹58 lakh on Punit Goenka, and ₹30 lakh on .
The core of this regulatory action lies in the unauthorized creation of an encumbrance over prime immovable property owned by —specifically, land parcels situated in Hyderabad—to secure private loan obligations raised by promoter-controlled entities. The order, authored by SEBI's quasi-judicial authority N. Murugan, highlights severe breaches of statutory duties, failure of internal corporate governance controls, deliberate suppression of material facts from public shareholders, and the illegal deployment of listed corporate assets for personal promoter benefit. This analytical study examines the factual sequence, statutory frameworks, legal doctrines, and regulatory precedents involved in this high-profile capital markets enforcement action.
Factual Anatomy of the Unauthorized Encumbrance
The genesis of the dispute traces back to December 2016, when four privately held corporate entities associated with the Essel Group borrowed an aggregate amount of ₹726 crore from lender Indiabulls Housing Finance Ltd (IHFL). While Essel Home Pvt. Ltd. acted as a co-borrower, multi-layered holding structures concealed the ultimate beneficial ownership of the borrowing companies. Comprehensive regulatory investigations subsequently revealed that these borrowing entities were completely owned and controlled by Subhash Chandra and his immediate family members through various corporate layers. Crucially, was neither a party to these private loan agreements nor a recipient of any portion of the ₹726 crore credit facility.
In November 2018, as underlying collateral values deteriorated across financial market portfolios, IHFL issued formal demand notices to the borrowing entities, requesting additional security cover to maintain agreed loan-to-value covenants. In response to this private promoter liquidity pressure, Subhash Chandra—acting in his capacity as Chairman of —executed a Deposit and Declaration Agreement (D&A) on December 27, 2018. Under this instrument, the original title deeds of 's Hyderabad land parcels were physically handed over to IHFL to create a first-ranking equitable mortgage as additional collateral for the private debts of the Essel Group entities.
SEBI’s detailed probe established that this pledge was executed under false pretenses. Chandra represented to the lender that the mortgage carried full authorization and approval from 's management and Board. However, official corporate records revealed that no prior approval was ever sought or granted by 's Audit Committee or Board of Directors. Furthermore, no public disclosures were made to the stock exchanges or included in statutory financial reporting. The physical title deeds remained pledged with IHFL until June 2020. The entire episode was falsely presented during statutory audit inquiries as a simple administrative misplaced-document issue, demonstrating an intentional effort to conceal material conflicts of interest from minority investors.
Key Statutory Provisions and Legal Frameworks
The legal apparatus applied by SEBI in this enforcement action rests upon three primary regulatory pillars: statutory prohibitions against market fraud under the SEBI Act and PFUTP Regulations, mandatory corporate governance mandates under LODR Regulations, and directorial fiduciary standards codified in the Companies Act, 2013.
1. SEBI Act, 1992 and PFUTP Regulations, 2003
Section 12A of the Securities and Exchange Board of India Act, 1992 explicitly prohibits any person from directly or indirectly employing any manipulative, deceptive, or fraudulent device or scheme in connection with the issue, purchase, or sale of securities listed on a recognized stock exchange.
Complementing Section 12A, the SEBI (Prohibition of Fraudulent and Unfair Trade Practices relating to Securities Market) Regulations, 2003 (PFUTP Regulations) define market fraud in expansive terms. Regulation 3 prohibits any person from engaging in fraudulent or unfair trade practices in securities transactions. Regulation 4(1) restricts entities from indulging in fraudulent acts that jeopardize overall market integrity. Specifically:
Regulation 4(2)(f) penalizes publishing or causing to be published misstatements or misleading information concerning listed companies.
Regulation 4(2)(k) addresses deceptive devices or schemes that obscure the true financial standing or asset backing of a listed company.
Regulation 4(2)(r) covers acts of siphoning, unauthorized diversion, or encumbrance of corporate assets that prejudice the interests of public equity investors.
SEBI held that using a listed company’s immovable asset as collateral for private promoter debt constitutes a fraudulent device. By exposing public enterprise assets to potential foreclosure risk for personal financial benefit, the noticees committed legal fraud against and its public shareholders.
2. SEBI LODR Regulations, 2015
The SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 establish rules for listed companies to maintain transparency and equity between controlling promoters and public investors. The order found severe violations of:
Regulation 4(1)(a) & (b): Core principles governing disclosure and governance, requiring key managerial personnel to act in good faith, with due diligence, care, and in the best interest of the entity and its shareholders.
Regulation 23: Mandates that all Related Party Transactions (RPTs)—including any creation of security, guarantee, or financial exposure for related parties—must receive prior approval from the Audit Committee.
Regulation 30: Mandates immediate public disclosure of material events, including encumbrances or creation of third-party rights over significant corporate assets.
Regulation 33 & Regulation 48: Mandates true and fair financial reporting, prohibiting omission or distortion of material liability and asset encumbrances.
3. Fiduciary Duties Under Section 166 of the Companies Act, 2013
Although SEBI operates as a specialized capital markets regulator, its evaluation of directorial conduct draws heavily upon general principles of corporate law codified under Section 166 of the Companies Act, 2013. Section 166 mandates that a director of a company shall:
Act in good faith to promote the objects of the company for the benefit of its members as a whole (Section 166(2)).
Exercise duties with due and reasonable care, skill, and diligence (Section 166(3)).
Avoid situations in which they have a direct or indirect interest that conflicts with the interest of the company (Section 166(4)).
Refrain from achieving or attempting to achieve any undue gain or advantage either to themselves or to their relatives, partners, or associates (Section 166(5)).
Subhash Chandra and Punit Goenka breached these fundamental fiduciary duties by prioritizing the liquidity demands of private promoter entities over the financial security and governance integrity of .
Judicial Analysis: Piercing the Layered Corporate Structure
A notable aspect of SEBI's 150-page order is the quasi-judicial authority’s refusal to accept formalistic defences. The noticees argued that had suffered no actual financial loss because the title deeds were eventually returned in June 2020 without lender foreclosure. SEBI firmly rejected this line of defence, reiterating established securities law jurisprudence: the offense of market fraud and governance breach is legally complete upon the unauthorized exposure of the listed company's asset to risk, regardless of whether actual financial loss subsequently materializes.
SEBI emphasized that the assets of a listed public company are held in fiduciary trust for all equity holders, including minority retail and institutional investors. A controlling promoter or executive director cannot treat the assets of a public listed enterprise as personal or family collateral.
The regulator also pierced corporate layers to connect the borrowing entities—Essel Home Pvt. Ltd. and related private firms—directly to Subhash Chandra and his family members. The investigation mapped equity holdings, directorships, and control structures to show that the ultimate beneficiaries of the ₹726 crore loan facilities were private family-owned entities. This established that Subhash Chandra used his position as Chairman Emeritus/Chairman and Punit Goenka used his position as MD & CEO to benefit family entities at the direct expense of .
Regulatory Enforcement Powers Under Sections 11, 11B, and 11(4)
To uphold capital market integrity, SEBI drew upon its broad statutory powers under Sections 11(1), 11(4), and 11B(1) of the SEBI Act, 1992. These sections empower the regulator to issue binding directions, debar entities from accessing capital markets, restrain individuals from holding managerial positions in listed companies, and impose monetary penalties to protect general investor interests.
The imposition of a one-year market ban on key corporate leaders sends a firm signal across Corporate India. It highlights that senior corporate executive positions do not shield individuals from legal accountability when public trust is compromised. The temporary two-month market access ban on further emphasizes that corporate entities must maintain internal compliance mechanisms to prevent unauthorized executive actions.
Broader Implications for India Inc. and Corporate Governance
This order reinforces several critical corporate governance principles across India's capital markets:
Strict Accountability for Related Party Transactions (RPTs): Transactions that directly or indirectly benefit controlling promoters must pass through independent Audit Committee scrutiny. Bypassing these procedures exposes executives to enforcement action.
Protection of Minority Shareholder Value: Institutional and retail investors rely on published disclosures to assess true enterprise value. Concealing asset encumbrances distorts financial valuation and misleads public investors.
Inadequacy of Post-Facto Cure: The argument that no financial loss occurred because title deeds were returned does not absolve executives of legal liability. Exposing corporate assets to default risk without authority constitutes a complete legal violation at the moment of execution.
Independent Board Oversight: The ruling underscores the non-negotiable responsibility of Audit Committees and independent directors to monitor physical asset safety and investigate audit flags promptly.
Searchable Legal FAQ Index
Navigation Index of Questions
FAQ 1: What specific regulatory violations led to SEBI's market bar on Subhash Chandra and Punit Goenka?
FAQ 2: What is a Deposit and Declaration Agreement (D&A), and why was its execution illegal in this case?
FAQ 3: How do SEBI LODR Regulations govern Related Party Transactions (RPTs) and asset encumbrances?
FAQ 4: What constitutes market fraud under SEBI PFUTP Regulations, 2003 in corporate asset misuse cases?
FAQ 5: What statutory duties under Section 166 of the Companies Act, 2013 were violated by the executives?
FAQ 6: What legal enforcement powers does SEBI exercise under Sections 11, 11B, and 12A of the SEBI Act, 1992?
FAQ 7: Why is exposing a listed corporate asset to risk illegal even if no financial loss occurs?
FAQ 8: What legal remedies are available to minority shareholders when promoters breach governance standards?
Detailed Answers to Legal Questions
FAQ 1: What specific regulatory violations led to SEBI's market bar on Subhash Chandra and Punit Goenka?
Answer: SEBI barred Subhash Chandra and Punit Goenka for one year following investigations that proved the unauthorized encumbrance of 's Hyderabad land parcels. The noticees pledged the title deeds of these listed assets to Indiabulls Housing Finance Ltd (IHFL) to secure ₹726 crore in private debts for promoter-controlled Essel Group entities. This action violated Regulations 3 and 4 of SEBI PFUTP Regulations, 2003 (prohibiting fraudulent trade practices), Regulations 4, 23, 30, 33, and 48 of SEBI LODR Regulations, 2015 (governing RPTs, material disclosures, and corporate governance principles), and Section 12A of the SEBI Act, 1992.
FAQ 2: What is a Deposit and Declaration Agreement (D&A), and why was its execution illegal in this case?
Answer: A Deposit and Declaration Agreement (D&A) is a legal instrument executed when physical title deeds of immovable property are deposited with a financial institution to create an equitable mortgage or security cover for credit facilities. In this case, Subhash Chandra executed a D&A on December 27, 2018, depositing 's original Hyderabad land deeds with IHFL. The execution was illegal because:
The property belonged to (a public listed company), while the borrowers were private Essel Group entities.
Chandra falsely declared that he had management and Board authorization.
No prior approval was granted by ZEEL's Audit Committee or Board of Directors.
The transaction was concealed from public shareholders and stock exchanges.
FAQ 3: How do SEBI LODR Regulations govern Related Party Transactions (RPTs) and asset encumbrances?
Answer: Under Regulation 23 of SEBI LODR Regulations, 2015, any transaction involving the transfer of resources, services, or obligations between a listed company and a related party—regardless of whether a price is charged—is an RPT. Providing corporate assets, guarantees, or security covers for a related party's debts requires prior approval from the company's Audit Committee. Furthermore, Regulation 30 requires immediate disclosure of any material encumbrance or third-party right created over listed corporate assets to stock exchanges, ensuring transparent market pricing.
FAQ 4: What constitutes market fraud under SEBI PFUTP Regulations, 2003 in corporate asset misuse cases?
Answer: Under the SEBI PFUTP Regulations, 2003, fraud includes any act, expression, omission, or concealment committed to induce another person to deal in securities, as well as any deceptive manipulation of corporate structures. In asset misuse scenarios, Regulation 4(2)(r) explicitly classifies the unauthorized encumbrance, diversion, or siphoning of a listed company's assets or funds for the benefit of promoters, directors, or related entities as a fraudulent practice. It deceives public shareholders regarding the enterprise's asset protection and risk exposure.
FAQ 5: What statutory duties under Section 166 of the Companies Act, 2013 were violated by the executives?
Answer: Section 166 of the Companies Act, 2013 outlines mandatory directorial duties. The executives violated:
Section 166(2): Duty to act in good faith to promote the objects of the company for the benefit of all members. Pledging listed assets for private debts compromised company interests.
Section 166(3): Duty to exercise due care, skill, and reasonable diligence.
Section 166(4): Duty to avoid direct or indirect conflicts of interest. Directing listed company assets to save family-owned entities created a direct conflict of interest.
Section 166(5): Prohibitions against attaining undue gain or advantage for self, relatives, or associates.
FAQ 6: What legal enforcement powers does SEBI exercise under Sections 11, 11B, and 12A of the SEBI Act, 1992?
Answer: Section 11 of the SEBI Act, 1992 gives SEBI the primary mandate to protect investor interests and regulate the securities market. Section 11B empowers SEBI to issue binding directions, including debarring individuals or corporate entities from accessing securities markets, directing disgorgement of wrongful gains, and removing key managerial personnel. Section 11(4) allows interim and final precautionary measures during or following investigations. Section 12A explicitly prohibits fraudulent, manipulative, or deceptive practices in capital markets.
FAQ 7: Why is exposing a listed corporate asset to risk illegal even if no financial loss occurs?
Answer: Under capital markets jurisprudence, the illegal act is complete when an executive exposes a public enterprise's asset to risk without statutory authority. Creating a mortgage gives the lender foreclosure rights in the event of default. The risk exposure itself diminishes the security profile of the listed entity and prejudices public investors who traded shares without knowledge of the encumbrance. Subsequent return of title deeds reduces financial injury but does not rectify the completed statutory fraud.
FAQ 8: What legal remedies are available to minority shareholders when promoters breach governance standards?
Answer: Minority shareholders have several legal remedies under Indian law:
Complaints to SEBI: Filing complaints through the SCORES portal triggers investigation under PFUTP and LODR regulations.
Class Action Suits: Section 245 of the Companies Act, 2013 allows shareholders to file class action suits before the National Company Law Tribunal (NCLT) seeking injunctions or damages against directors for fraudulent acts.
Oppression and Mismanagement Claims: Sections 241 and 242 of the Companies Act, 2013 enable shareholders holding required capital thresholds to apply to NCLT against actions prejudicial to public interest or company stability.
Derivative Actions: Shareholders can seek judicial enforcement of company rights when controlling management refuses to act against wrongdoers.
Comparative Regulatory Framework Summary
To clarify the legal provisions discussed in the SEBI order and analytical study, the table below outlines the governing rules, legal sections, compliance requirements, and regulatory implications:
Conclusion: Reaffirming Institutional Trust in Indian Capital Markets
The final order passed by SEBI against Subhash Chandra, Punit Goenka, and serves as a precedent in Indian corporate law. By enforcing compliance with PFUTP and LODR regulations, the market regulator has reinforced the fundamental principle that corporate governance is an enforceably binding statutory duty rather than a discretionary guideline.
Listed enterprises belong to their entire body of public shareholders. Promoters and executives hold corporate power in fiduciary trust and cannot deploy public assets as financial cushions for private debt. As Corporate India matures, regulatory interventions of this nature provide essential safeguards for domestic and foreign institutional investors, strengthening transparency, accountability, and ethical standards across Indian financial markets.
Statutory / Regulatory Framework — Relevant Sections / Rules — Compliance Requirements — Regulatory Implication of Non-Compliance
SEBI Act, 1992 — Sections 11, 11B, 11(4), 12A — Absolute prohibition on fraudulent, deceptive, or manipulative devices in listed securities — Quasi-judicial debarment orders, market bans, structural restrictions, monetary penalties
SEBI PFUTP Regulations, 2003 — Regulations 3(a)-(d), 4(1), 4(2)(f), (k), (r) — Strict prohibition against siphoning, unauthorized encumbrance, or misrepresentation of company assets — Legal classification of transaction as market fraud, penal proceedings, market ban
SEBI LODR Regulations, 2015 — Regulations 4(1), 23, 30, 33, 48 — Prior Audit Committee approval for RPTs, immediate public disclosure of asset encumbrance — Regulatory penalty on company and executives, suspension of market access, corporate governance sanction
Companies Act, 2013 — Sections 166, 184, 185, 188 — Fiduciary duty of loyalty, care, conflict avoidance, prohibition on unauthorized loans/guarantees — Personal liability of directors, NCLT oppression claims, disqualification of directorships