
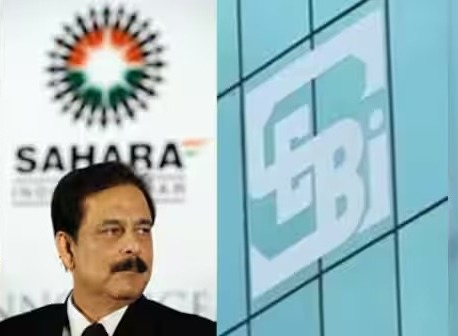
SEBI Moves Supreme Court Against Sahara Managers’ Relief in OFCD Case
Apex Court to Revisit Investor Protection in Controversial Debenture Scheme
Landmark Litigation Tests SEBI’s Regulatory Powers
By Our Legal Correspondent
New Delhi: June 15, 2026:
The Securities and Exchange Board of India (SEBI) has approached the Supreme Court challenging relief granted to managers of a Sahara Group entity in the long-running case concerning Optionally Fully Convertible Debentures (OFCDs). This case, one of the most complex financial litigations in India, continues to test the boundaries of securities regulation, investor protection, and judicial oversight.
Background of the Case
The Sahara OFCD case dates back to 2008–2011, when Sahara India Real Estate Corporation Ltd. (SIRECL) and Sahara Housing Investment Corporation Ltd. (SHICL) raised over ₹24,000 crore from millions of investors through OFCDs. SEBI alleged that these were public issues requiring compliance with the Companies Act, 1956 and the SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2009 (ICDR Regulations).
The Supreme Court in 2012 ordered Sahara to refund the money to investors with interest, holding that the OFCDs were indeed public issues. Since then, enforcement has been ongoing, with SEBI seeking to recover funds and Sahara contesting various aspects.
The latest development involves relief granted to managers of Sahara entities, which SEBI has now challenged before the Supreme Court.
Key Legal Provisions Discussed
Companies Act, 1956 (now Companies Act, 2013)
Section 67(3): Defines private placement and limits number of investors. Sahara exceeded this limit, making the issue public.
Section 73: Requires companies making public issues to seek stock exchange listing and comply with SEBI regulations.
SEBI Act, 1992
Section 11: Empowers SEBI to protect investors and regulate securities markets.
Section 11B: Grants SEBI authority to issue directions to companies and individuals violating securities laws.
ICDR Regulations, 2009
Mandates disclosure, prospectus filing, and investor protection measures for public issues.
Sahara’s OFCDs bypassed these requirements.
Supreme Court’s 2012 Judgment (Subrata Roy Sahara v. SEBI)
Held Sahara’s OFCDs to be public issues.
Directed refund of ₹24,000 crore with 15% interest.
Established SEBI’s jurisdiction over hybrid instruments like OFCDs.
SEBI’s Arguments in Current Appeal
Relief granted to Sahara managers undermines enforcement of the 2012 judgment.
Managers played a role in facilitating the OFCD scheme and cannot be absolved of responsibility.
Investor protection requires strict accountability of intermediaries and managers.
Court’s Observations in Earlier Rulings
Investor Protection Priority
Courts have consistently emphasized safeguarding small investors.
Sahara’s OFCD scheme was criticized for lack of transparency.
Jurisdiction of SEBI
The Supreme Court affirmed SEBI’s jurisdiction even over unlisted companies issuing securities to the public.
This expanded SEBI’s regulatory reach.
Corporate Accountability
Managers and directors cannot escape liability by claiming ignorance.
Corporate governance requires responsibility at all levels.
Broader Implications
For SEBI’s Regulatory Powers
The case tests SEBI’s ability to enforce compliance against powerful conglomerates.
A ruling against SEBI could weaken its authority.
For Corporate Governance
Reinforces accountability of managers and directors in financial schemes.
Prevents misuse of hybrid instruments to bypass regulations.
For Investors
Ensures that investor protection remains paramount.
Highlights risks of investing in unregulated schemes.
Judicial Precedents Referenced
Subrata Roy Sahara v. SEBI (2012): Landmark ruling on OFCDs as public issues.
SEBI v. Gaurav Varshney (2016): Clarified SEBI’s jurisdiction over private placements exceeding investor limits.
Common Cause v. Union of India (2014): Reinforced public trust doctrine in allocation of resources.
The Decision Awaited
The Supreme Court will now decide whether relief granted to Sahara managers stands or whether SEBI’s enforcement powers must prevail. The ruling will have far-reaching consequences for securities regulation and corporate accountability in India.
FAQ Section (Approx. 700–800 words)
FAQ Index: SEBI vs Sahara OFCD Case
Q1: What are OFCDs? A: Optionally Fully Convertible Debentures are hybrid instruments that can convert into shares at a later date.
Q2: Why did SEBI challenge Sahara’s OFCDs? A: Because Sahara raised funds from millions of investors without complying with public issue regulations.
Q3: What did the Supreme Court rule in 2012? A: It held Sahara’s OFCDs to be public issues, ordered refund of ₹24,000 crore with interest, and affirmed SEBI’s jurisdiction.
Q4: What is SEBI’s current appeal about? A: SEBI is challenging relief granted to Sahara managers, arguing they must be held accountable.
Q5: Which laws govern public issues in India? A: The Companies Act, SEBI Act, and ICDR Regulations.
Q6: What constitutional principles are involved? A: Investor protection under Article 14 (Equality before law) and corporate accountability under the public trust doctrine.
Q7: Can managers escape liability in such cases? A: Courts have held that managers and directors are responsible for compliance and cannot plead ignorance.
Q8: How does this case affect investors? A: It reinforces the need for transparency and compliance in financial schemes to protect investors.
Q9: What precedents were cited? A: The 2012 Sahara judgment, SEBI v. Gaurav Varshney (2016), and Common Cause v. Union of India (2014).
Q10: What is the broader impact of this ruling? A: It will determine the strength of SEBI’s enforcement powers and set standards for corporate governance in India.