
Scholarship Taxation: Relief for Students, But with Caveats
Section 10(16) Provides Full Exemption for Genuine Scholarships
Stipends and Employer Aid May Still Be Taxable
By Vishwas Kumar
New Delhi: April 18, 2026:
Let’s take another personal tax that is widely searched and often misunderstood: Tax on Scholarships and Education Assistance. With more students and professionals receiving scholarships, stipends, or employer-sponsored education aid, this is a common area of confusion.
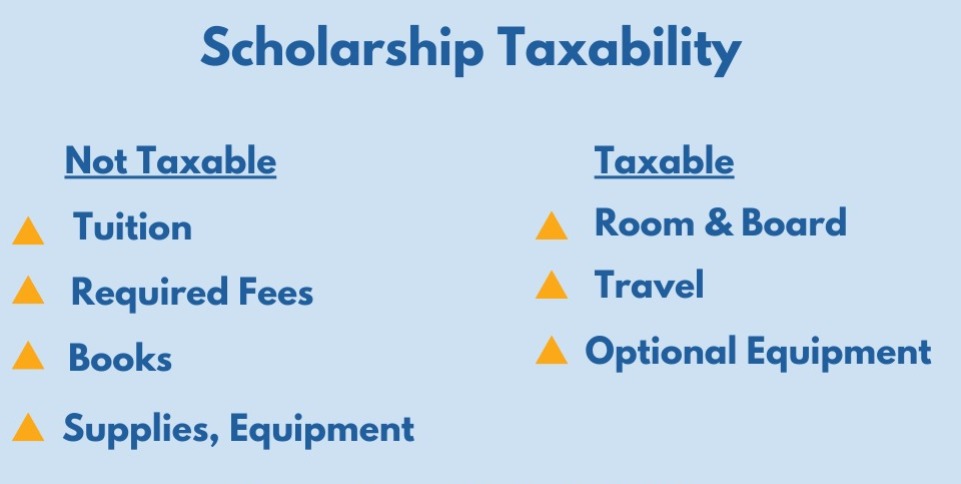
Scholarships and education assistance are vital for students and professionals pursuing higher studies. While genuine scholarships are exempt under Section 10(16) of the Income Tax Act, stipends and employer-sponsored education benefits may be treated differently. With rising costs of education and more financial aid programs, clarity on taxation rules ensures compliance and avoids surprises.
One of the most important rulings on this issue is Lakshmi Amma & Anr. v. Talengalanarayana Bhatta & Anr., where the Supreme Court clearly examined the legal principles governing property rights, evidentiary standards, and dispute resolution. This landmark judgment continues to guide courts in resolving similar inheritance and civil disputes across India.
Analytical Overview
1. Scholarships
- Fully exempt under Section 10(16) if granted to meet education costs.
- Applies to scholarships from universities, trusts, or government bodies.
- No monetary limit on exemption.
2. Stipends
- Often treated as salary income if linked to employment or training.
- Taxable at slab rate.
- Example: Medical internship stipends are generally taxable.
3. Employer-Sponsored Education Aid
- If employer pays directly for employee’s education, it may be treated as a perquisite and taxed.
- If aid is structured as a scholarship for employee’s children, exemption may apply.
4. Foreign Scholarships
- Exempt if granted for education.
- However, living allowances or stipends may be taxable.
- Double Taxation Avoidance Agreements (DTAA) may provide relief.
5. Documentation Essentials
- Scholarship award letter.
- Proof of educational expenses.
- Employer’s certificate for education aid.
- Tax residency certificate for foreign scholarships.
6. Risks & Challenges
- Confusing stipends with scholarships can lead to wrong filings.
- Employer aid often misclassified.
- Non-disclosure of taxable stipends may attract penalties.
Quick Comparison Table
| Type | Tax Treatment |
|---|---|
| Scholarship (education cost) | Fully exempt |
| Stipend (training/employment) | Taxable as salary |
| Employer aid (employee education) | Taxable perquisite |
| Employer aid (children scholarship) | Exempt |
| Foreign scholarship | Exempt (education), taxable (stipend) |
[RESEARCH RESOURCES]
Explore all probate-related rulings here. Click the link here: https://www.courtkutchehry.com/pages/blog/123-supreme-court-judgments-on-wills/
BUY & READ BOOK, WILL WRITING SIMPLIFIED, By Dr Ravinder Kumar Anand. [📘 Buy Will Writing Simplified online: Amazon | Flipkart ]
FAQs on Scholarship & Stipend Taxes
Q1. Are scholarships taxable?
No, genuine scholarships for education are fully exempt under Section 10(16).
Q2. Is a stipend taxable?
Yes, stipends linked to employment or training are taxable as salary.
Q3. What about employer-sponsored education?
If for employee’s own education, it is taxable; if structured as scholarship for children, it may be exempt.
Q4. Are foreign scholarships taxable?
Education scholarships are exempt, but stipends or living allowances may be taxable.
Q5. Do I need to declare scholarships in ITR?
Exempt scholarships should be disclosed under exempt income.
Q6. Can I claim deductions on stipends?
No, stipends are treated as salary income without special deductions.
Q7. What documents are needed?
Scholarship award letter, expense proof, employer certificate, and DTAA documents if applicable.
Conclusion
Scholarship taxation is straightforward—genuine scholarships are exempt, but stipends and employer aid may be taxable. Students and professionals must distinguish between the two and maintain proper documentation to ensure compliance.